
Grocery bills have stayed high for American households, and shoppers keep searching for stores that offer good prices for healthy food. One of Wall Street’s most respected firms thinks a family-run grocer fits that description.
Bank of America started coverage of Natural Grocers by Vitamin Cottage (NGVC) with a Buy rating and a $35 price target, which points to roughly 20% gains from where the stock closed on Sept. 18.
Shares increased 5.66% that day to $30.98, adding to a 25.43% run so far in 2026.
BofA sets a $35 price target on Natural Grocers stock
Bank of America analyst Vicky Liu started coverage on Natural Grocers with a Buy rating and a $35 price target, according to a BofA Global Research report shared with me.
Liu is a CFA and research analyst at BofA Securities, and the report identifies affordable pricing, attractive new-store economics, and expansion into small markets as the main reasons for the call.
Liu expects Natural Grocers to grow revenue by about 6% to 7% each year, add 4% to 5% new stores annually, and keep expanding its EBITDA margin.
“NGVC’s ‘Always Affordable’ pricing should resonate as pressured consumers seek value amidst an inflationary environment,” she wrote.
Shares closed at $30.98 on Sept. 18, up 5.66% for the day and 25.43% year to date. The stock still trades at 13 times forward earnings, which is a discount compared to peers, and BofA argues that it doesn’t fairly reflect the company’s growth path or its return on invested capital of about 16%.
It also pays a quarterly dividend of $0.15 per share, or about 1.94% at the current price.
Cyrus McCrimmon / Getty Images
How Natural Grocers earns its money
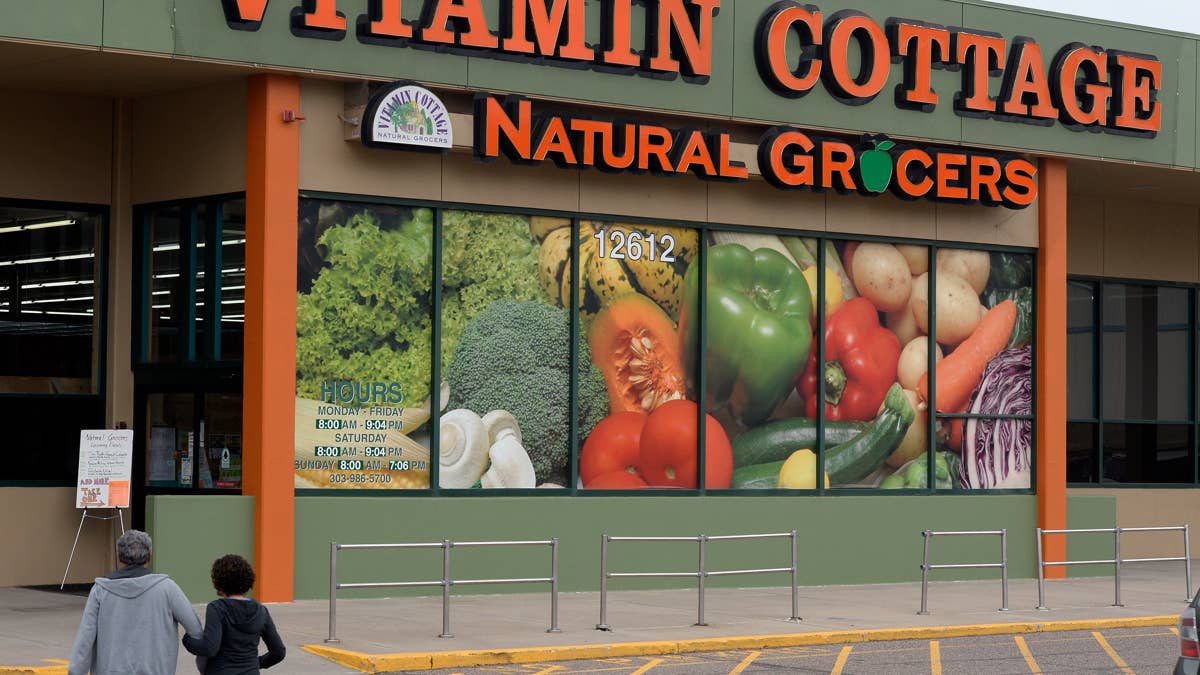
Natural Grocers is a family-run specialty grocer founded in 1955 that sells organic produce, natural groceries, body care products, and dietary supplements. The chain runs 174 stores across 22 states, most of them in smaller towns and cities that larger organic-focused chains often skip, according to a company press release.
Its stores use a small-box format with about 20,000 stock-keeping units, which is a fraction of what a typical supermarket carries. The company also skips full-service deli counters and fresh meat cases, which keeps labor and equipment costs lower than at bigger rivals.
Those choices help it turn a profit in towns that couldn’t support a large Sprouts Farmers Market or Whole Foods.
More Grocery Stocks:
- Kroger loses $12 billion as customers change course
- Target is taking on Walmart with a major grocery move
- Bank of America sees 21% upside in this beverage stock
BofA notes that Natural Grocers’ pricing runs about 15% below Sprouts Farmers Market (SFM), one of its most direct rivals. That approach also lifts its earnings-before-interest-and-taxes margin above larger conventional grocers.
Private label products still make up only 10% of its sales, well behind peers that are at over 25%, which BofA sees as an untapped area for margin growth.
“We believe the market underestimates NGVC’s growth runway and margin potential,” Liu said.
DoorDash and new-store growth could accelerate results
Unit growth and e-commerce stand out in the BofA call. Natural Grocers only operates in 22 states, so it has room to grow, and BofA expects the company to open 4% to 5% more stores each year.
Those new stores also pay back well. By year five, each one usually returns 25% to 30% in cash on what it cost to build, which lets Natural Grocers enter smaller towns where bigger natural-food chains can’t make profit.
Natural Grocers also announced a nationwide DoorDash delivery partnership in early September, and online sales still make up only about 2% of revenue. That means every new online buyer adds meaningfully to sales.
Related: Beverage giant wants to take over Halloween in bold new plan
“We see incremental growth opportunities from e-commerce expansion as the recently launched DoorDash partnership should drive transactions and new customer acquisition,” Liu wrote.
Raquel Isely, Natural Grocers’ vice president of marketing, said in a company press release that the partnership “gives customers another convenient way to shop our stores while continuing to enjoy the quality standards, value and trusted products that define the Natural Grocers experience.”
Risks investors should weigh before buying NGVC shares
BofA points out a few risks in the report. Shopper visits have slowed as buyers watch their spending more carefully, and the higher-margin supplements business has not been getting much of a lift from inflation, which usually helps pricing.
The bank also notes that no one can say for sure when store traffic will pick up again, even though the company is spending more on marketing and digital tools to bring shoppers in. If those efforts take longer to work, earnings could disappoint again.
The most recent quarter is a good example. Natural Grocers came in short on both earnings and revenue expectations, missing by 7.69% on earnings and 3.58% on revenue.
Anyone thinking about buying may want to wait for the next earnings report first, and keep the position small since NGVC is a small-cap stock with lower trading volume. Small purchases spread over the next few months can also reduce the risk of paying too much at once.
Related: Starbucks launches 4 new fall items after Pumpkin Spice Latte debut
